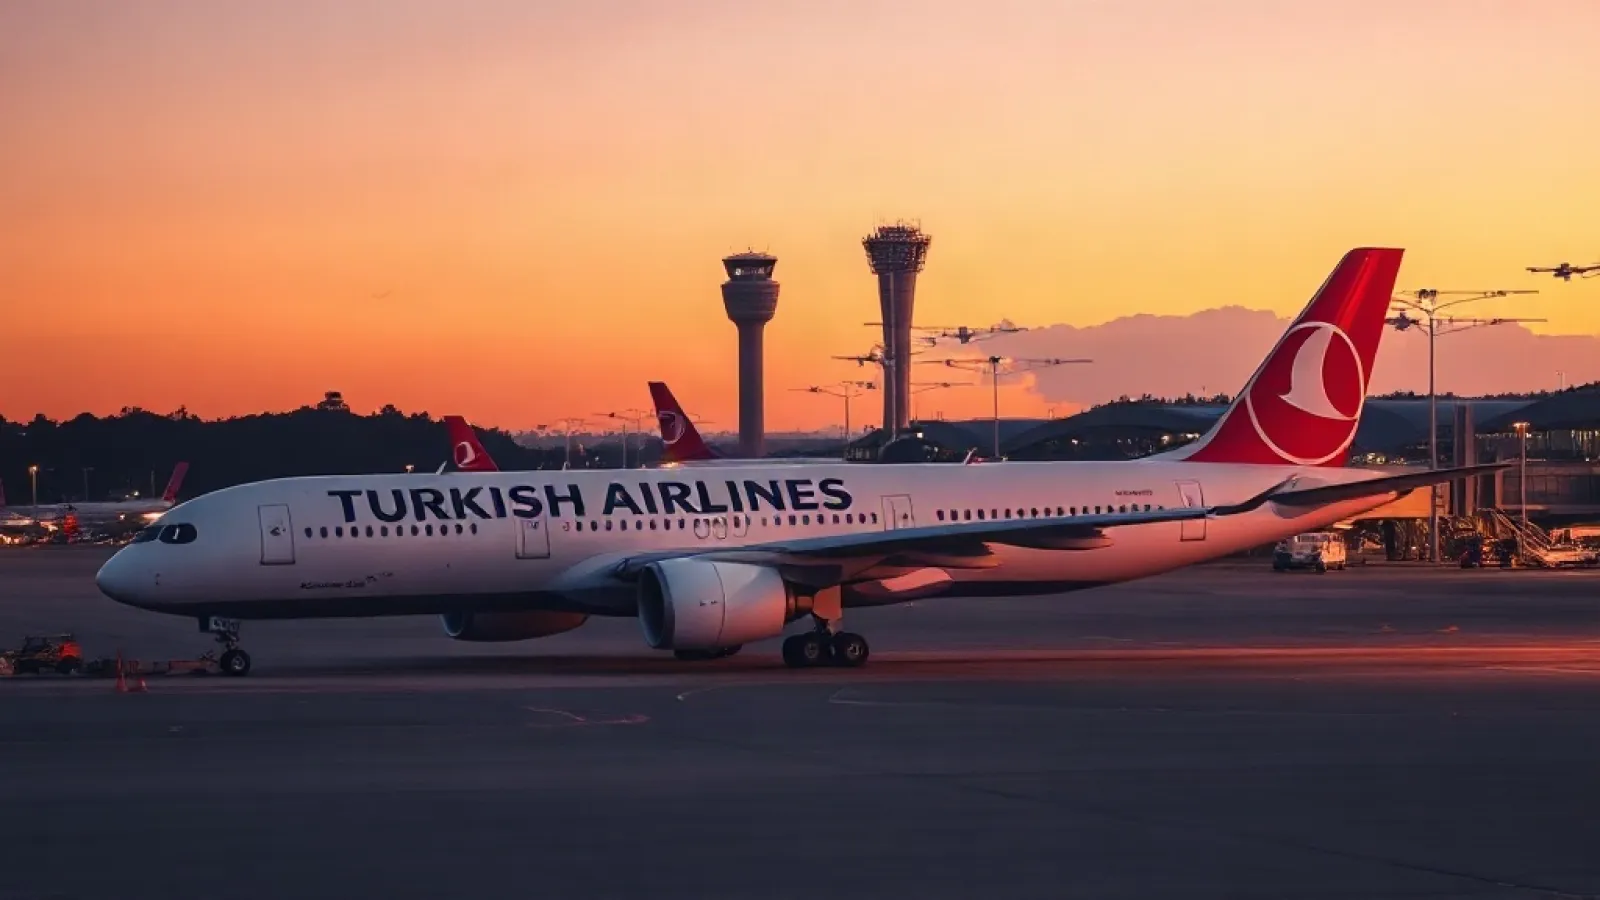
Turkish Airlines has removed 11 destinations from its future schedules, according to a report published on 21 September 2026, in a network revision spanning the United Kingdom, Europe and Africa. Separately, Corendon is reducing its UK network from six airports to three for the summer 2027 season.
The two moves land in the same week and point to capacity being reallocated rather than simply withdrawn. For trade buyers, the immediate consequence is a narrower set of direct options on the affected routes and a heavier reliance on connecting itineraries.
What is changing
Turkish Airlines' schedule adjustment removes 11 destinations from future planning. The carrier has not framed the change as a withdrawal from the regions concerned; the effect, however, is that city pairs previously served non-stop will require a connection through the airline's hub or an alternative carrier.
Corendon's change is more structural. Its UK footprint falls from six airports to three for summer 2027, halving the number of British departure points from which its seats can be sold. Summer 2027 inventory is already being loaded by tour operators and bedbanks, so the reduction lands inside the booking window for the peak season rather than after it.
Why it matters
Route cuts of this kind are rarely neutral for the wider travel trade. Airlines trim frequencies and destinations when aircraft, crew or expected returns do not justify the flying, and the capacity is then redeployed where demand is stronger. The destinations that lose service absorb the loss through longer journey times and, in many cases, higher fares as remaining seats are priced against reduced supply.
For tour operators and DMCs, the practical exposure sits in contracted programmes. Packages built around direct flights from a specific UK airport may need to be re-sourced, re-priced or rerouted through a different departure point. Where Corendon was one of a limited number of carriers serving a regional airport, the alternatives may involve a domestic positioning flight before the international sector — a cost and a friction point that has to be reflected in the selling price.
Bedbanks and dynamic packagers face a similar problem in reverse: their systems surface whatever combination of flights and rooms is available, so a thinner direct-flight map pushes more itineraries through hubs. That tends to lengthen the total journey and can shift the balance of demand towards destinations that retain non-stop links.
There is also a competitive dimension. Capacity removed by one carrier is capacity another can absorb, and the airports losing service will be lobbying for replacement routes. For the trade, the window between now and summer 2027 is the period in which those gaps are either filled or become permanent features of the network map.
Both changes are schedule decisions taken ahead of the season they affect, which gives the trade time to adjust — but only if the revised inventory is reflected in systems and contracts early enough to be sold.